Markets Rewarded Proof and Penalized Uncertainty
This week’s market behavior repeatedly separated strong execution from incomplete narratives, rewarding companies that converted demand into clearer growth while punishing weaker guidance, margin pressure, execution questions and elevated expectations.
A Week Where Evidence Mattered More Than the Story
Across technology, consumer stocks and emerging growth themes, the same pattern appeared repeatedly: investors responded less to the existence of an attractive narrative and more to evidence that the narrative was translating into growth, profitability, visibility or execution.
Dell Technologies (DELL), Snowflake (SNOW) and DocuSign (DOCU) provided clearer operating evidence and stronger outlooks. Broadcom (AVGO), MongoDB (MDB), Palo Alto Networks (PANW) and Zscaler (ZS) all delivered elements of strong performance, yet their shares faced pressure when margins, guidance or expectations complicated the picture. Tesla (TSLA) provided an even sharper example as enthusiasm around Cybercab gave way to questions about regulation and production scale.
The backdrop added another layer of discipline. A stronger-than-expected August jobs report increased expectations for a September Federal Reserve rate hike, Treasury yields had already moved higher, and Brent crude had moved above $90 following renewed U.S.-Iran fighting. Different catalysts produced different company-specific outcomes, but the recurring market behavior was similar: evidence, visibility and execution carried more weight than broad themes alone.
Key Points
- Dell (DELL), Snowflake (SNOW) and DocuSign (DOCU) showed how stronger growth, adoption and outlook visibility could support positive reactions even as AI investment altered business economics.
- Broadcom (AVGO), MongoDB (MDB), Palo Alto Networks (PANW) and Zscaler (ZS) showed the opposite side of the pattern as strong results were outweighed by margin pressure, slower growth expectations or an already demanding expectations bar.
- Tesla (TSLA), Adobe (ADBE) and Lululemon (LULU) reinforced the same behavior outside straightforward earnings comparisons as execution, strategic clarity and future visibility became central to market reactions.
The Repeating Pattern
The week's most consistent behavior was not simply enthusiasm for artificial intelligence or concern about higher interest rates. It was a repeated distinction between potential and demonstrated progress.
That distinction was particularly clear within technology.
Dell Technologies reported record fiscal second-quarter revenue as AI server orders accelerated, infrastructure sales surged and its AI backlog reached $95 billion. The company also raised fiscal 2027 guidance sharply. The combination provided measurable demand, backlog visibility and a stronger outlook, and DELL shares moved higher.
Snowflake presented a related case. AI adoption increased platform consumption, product revenue accelerated and management raised its full-year outlook. SNOW rallied even though the company lowered product gross-margin guidance as AI workloads became a larger part of its mix. The market response suggested that the stronger growth trajectory carried enough weight to offset the disclosed profitability tradeoff.
DocuSign also connected AI adoption with operating evidence. Its Intelligent Agreement Management platform gained traction while profitability and free cash flow improved, and management raised its fiscal 2027 annual recurring revenue growth outlook.
A similar reaction was observed in Yext (YEXT), where shares rose after the company reported a 31% adjusted EBITDA margin, stronger enterprise momentum and broader AI-search capabilities through Scout and Corvo AI.
These examples differed in business model and scale, but the outcome followed a recognizable pattern: growth narratives were better received when accompanied by improving operating metrics or greater visibility.
How Markets Responded Across Events
The inverse pattern was just as visible.
Broadcom reported a 221% increase in AI semiconductor revenue, yet AVGO fell about 6%. The issue was not a lack of AI demand. Investors instead focused on slightly weaker-than-expected fourth-quarter revenue guidance and pressure on gross margins from a heavier mix of custom AI accelerators.
MongoDB also beat fiscal second-quarter revenue and earnings estimates and raised its full-year outlook. Yet MDB fell sharply because Atlas growth remained near 29% and management indicated slower cloud growth in the third quarter.
Palo Alto Networks delivered stronger-than-expected fiscal fourth-quarter results and an upbeat fiscal 2027 outlook as AI-related security demand strengthened. PANW nevertheless declined sharply because the company entered the report with elevated expectations following a major rally.
Zscaler followed a similar path. The company beat quarterly revenue and earnings expectations, but ZS fell as investors concentrated on slower fiscal 2027 growth, weaker free cash flow and a back-end-weighted outlook.
Despite different catalysts, outcomes followed the same underlying behavior: good results were not automatically enough when investors could identify a weaker element in the forward picture.
That pattern extended beyond quarterly earnings.
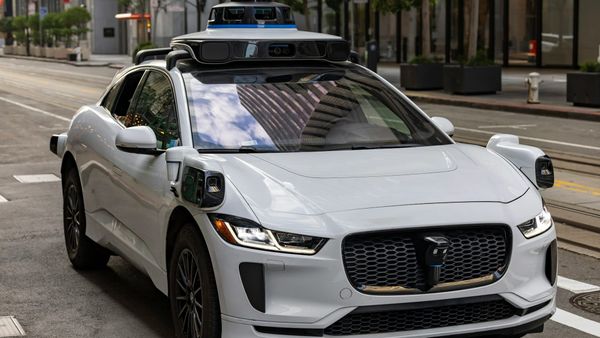
Tesla began the week with shares climbing more than 5% as attention centered on Cybercab activity, Full Self-Driving developments and plans for 100 GW of annual solar-production capacity. Cybercab then entered commercial service in Austin and Tesla opened commercial purchase inquiries. Yet the later reaction reversed: TSLA fell 5.9% as limited launch details, an NHTSA audit and unresolved production questions shifted attention from the event itself to regulatory and scaling execution.
Adobe provided another example of the market demanding strategic clarity. Its CEO transition and the departure of its creative-business leader sent ADBE sharply lower as leadership continuity became intertwined with existing concerns about the company's response to AI disruption.
Lululemon showed the same pattern in consumer retail through a more traditional operating problem. The company cut its full-year outlook after second-quarter revenue declined and comparable sales weakened across key markets. LULU fell sharply as weaker traffic, product pressure and an incoming CEO transition reduced visibility.
Even expansion initiatives were not treated uniformly. JetBlue (JBLU) expanded premium domestic travel through BlueFirst, while Carnival (CCL) connected cruise loyalty more closely with everyday spending through Carnival Rewards and a new Mastercard. Both strategies targeted deeper customer engagement, but both stocks remained under pressure. Strategic expansion alone did not override the market's broader assessment of the businesses.
What This Behavior Suggests
This pattern appeared across AI infrastructure, software, cybersecurity, mobility and consumer businesses.
Artificial intelligence remained a powerful operating theme, but the week's reactions showed that "AI exposure" was not functioning as a uniform market catalyst.
Nvidia (NVDA) continued pushing beyond GPUs through custom-chip connectivity, infrastructure investments and potential software expansion while projecting 70% fiscal 2028 revenue growth and describing demand as exceeding available supply. Microsoft (MSFT), meanwhile, reorganized its financial reporting around two new segments and committed to disclosing Azure revenue dollars quarterly for the first time, increasing transparency around its cloud business as AI reshapes the company.
CrowdStrike (CRWD), Palantir (PLTR) and Datadog (DDOG) were identified as companies showing strong growth linked to AI demand, while Salesforce (CRM) continued adapting its platform and Intuit (INTU) faced questions about slower growth and pricing.
The divergence across those names reinforced the same conclusion drawn from Broadcom, Snowflake, MongoDB and Zscaler: markets were differentiating between companies according to the quality, economics and visibility of AI-related growth rather than treating the sector as a single trade.
The same differentiation appeared around physical infrastructure.
Google's geothermal agreement with Fervo Energy converted part of an existing partnership into 396 megawatts of contracted capacity, with an option that could take Google's purchase close to 1 gigawatt by 2030. Fervo shares surged.
SLB (SLB) expanded beyond traditional oilfield services through its $3.4 billion acquisition of Kelvion, adding thermal-management capabilities to its growing data-center infrastructure business.
Caterpillar (CAT) reported a record second quarter as construction, power generation and AI infrastructure contributed to a changing growth mix, supported by a $72 billion backlog.
Those stories connected AI to power, cooling, equipment and physical capacity rather than software alone. Yet the broader market pattern remained consistent: tangible capacity, contracts and backlog carried more informational weight than thematic exposure by itself.
The macro environment reinforced that selectivity without producing one uniform reaction.
The August employment report showed 162,000 new jobs, nearly triple expectations, strengthening the case for a September Federal Reserve rate hike. Earlier in the week, the 10-year Treasury yield had moved toward 4.8% and the 30-year yield remained above 5.2%, raising borrowing costs while inflation and federal debt stayed in focus.
Oil added another source of pressure. Renewed U.S.-Iran strikes pushed Brent above $90 as Gulf supply constraints and shrinking inventories renewed energy-driven inflation concerns.
At the same time, the broader U.S. economy continued to show resilience through consumer spending, corporate profits and AI investment while persistent inflation, weak hiring conditions in earlier data and affordability pressures complicated the picture.
The result was not a simple risk-off market. Apple (AAPL), for example, gained more than 2% during its leadership transition under CEO John Ternus even as broader technology stocks were under pressure. Robinhood (HOOD) and Circle (CRCL) rose roughly 15% as fintech expansion, prediction-market growth and stablecoin policy developments drove crypto-linked stocks higher.
The market continued rewarding specific evidence even while macro constraints increased.
Why This Context Matters
Weekly market behavior can reveal more than a list of winning and losing stocks because similar reactions across unrelated events can expose the standards markets are applying.
This week, those standards repeatedly centered on four elements: execution, guidance, profitability and visibility.
Dell combined AI demand with backlog and a stronger outlook. Snowflake combined accelerating consumption with higher guidance. DocuSign combined AI adoption with profitability and free cash flow.
Broadcom had powerful AI growth but encountered margin pressure and softer guidance. MongoDB beat expectations but offered weaker near-term cloud growth. Zscaler produced strong quarterly numbers but a slower fiscal 2027 outlook. Palo Alto Networks executed well but faced an expectations bar raised by its prior rally.
Tesla turned a highly anticipated product milestone into an execution test once regulatory and scaling details moved to the foreground. Adobe's leadership change intensified scrutiny of its AI strategy. Lululemon's weaker demand and guidance reset reduced confidence in the near-term business trajectory.
The recurring behavior was therefore not confined to one industry or one type of catalyst. Markets repeatedly moved from narrative to verification.
That distinction was also visible in longer-duration growth stories. Eli Lilly (LLY) agreed to acquire Merida Biosciences for up to $2.875 billion, adding an early-stage precision-immunology platform as it diversified beyond obesity and diabetes. LLY moved lower as investors weighed the longer-term opportunity against the early development stage.
Uber (UBER) continued positioning itself as a platform for autonomous transportation through partnerships rather than building its own robotaxi fleet, while the longer-term impact of regulation and autonomous competition remained unresolved.
Across both cases, expansion created opportunity, but the market still had to assess how distant, measurable or executable that opportunity was.
Conclusion
The week's strongest recurring market behavior was a preference for demonstrated progress over broad narrative strength.
AI remained central to results from Nvidia, Dell, Broadcom, Snowflake, CrowdStrike, Palo Alto Networks, Zscaler and Microsoft, but the market did not treat those companies uniformly. Backlog, accelerating consumption, stronger guidance and profitability supported some reactions, while margin pressure, slower expected growth and elevated expectations weighed on others.
Tesla, Adobe, Lululemon and Eli Lilly showed that the same discipline extended beyond AI earnings. Product launches, leadership changes, acquisitions and strategic initiatives were all judged against questions of execution and visibility.
Meanwhile, higher Treasury yields, oil above $90 and a stronger August jobs report kept inflation and interest-rate risk in the background.
Despite different catalysts, outcomes repeatedly followed the same pattern: the market rewarded evidence that improved visibility and became less forgiving when future execution remained uncertain.
FAQs
What was the main market pattern this week?
The main pattern was a preference for measurable execution and clearer visibility over broad growth narratives alone. Dell, Snowflake and DocuSign paired growth with stronger operating evidence, while Broadcom, MongoDB and Zscaler faced pressure despite strong results because investors focused on margins, guidance or slower expected growth.
Why did some AI stocks fall despite strong growth?
Strong AI growth was not always enough when other parts of the outlook weakened. Broadcom reported 221% AI semiconductor revenue growth but fell as investors focused on gross-margin pressure and slightly weaker-than-expected guidance, while Palo Alto Networks declined despite strong results because expectations were already elevated.
How did Tesla fit the week's broader pattern?
Tesla fit the same pattern because enthusiasm shifted from the Cybercab launch itself to questions about execution. TSLA initially gained as investors focused on autonomy and Cybercab activity, then fell 5.9% after limited launch details, an NHTSA audit and unresolved production questions moved regulatory and scaling risks into focus.
Did macro conditions affect the week's market behavior?
Yes. A stronger-than-expected August jobs report increased expectations for a September Federal Reserve rate hike, while the 10-year Treasury yield moved toward 4.8%, the 30-year remained above 5.2%, and Brent crude rose above $90 following renewed U.S.-Iran fighting.
Was AI still an important market theme?
Yes. AI remained central across Nvidia, Dell, Broadcom, Snowflake, Microsoft, CrowdStrike, Palo Alto Networks and other companies, but market reactions increasingly depended on how effectively each business translated AI demand into revenue growth, margins, backlog, cash flow or clearer future visibility.
This article was created with AI assistance and reviewed by an editor. For details, please refer to our Terms of Use.
Go Beyond the Market Brief with Market Edge
Follow SharperTrades’ complete approach to trading and investing, combining active trade opportunities through Block Orders, long-term research through Stock Investor, and structured market education through the Swing Trading Masterclass. Try Market Edge for $19 your first month →
Explore Research with Stock Investor
Stock Investor is SharperTrades’ platform for long-term investing research and portfolio management. Members receive research reports, portfolio updates, conviction tracking, and in-depth analysis designed to support disciplined investment decisions.
Explore Active Trading & Income Strategies
Block Orders tracks institutional activity and highlights active trade setups and price behavior across long and short opportunities.
For options-focused traders, Essential Option Income provides a structured approach to options income strategies, while Pro Option Trader offers a broader range of options strategies and trade opportunities.
Think More Clearly with SteadyCapital
SteadyCapital is SharperTrades’ decision-support system for long-term investors, built around the SteadyCapital Method™. Review investment ideas, challenge assumptions, evaluate valuation and risk, compare companies, and think through important buy, hold, add, trim, or sell decisions before you act.
Risk Disclosure
All content is provided for educational purposes only and does not constitute investment advice. Trading involves risk, and past performance is not indicative of future results. Please review our full Risk Disclosure for additional information.