Strong Jobs Report Raises Fed Hike Odds as Trump Escalates Pressure for Lower Rates
The U.S. added 162,000 jobs in August, nearly triple expectations, strengthening the case for a September Fed rate hike. Stocks and bonds reacted as President Donald Trump simultaneously demanded lower rates and threatened trade restrictions against deficit countries.
Strong Hiring Puts Inflation Back at the Center of the Fed Debate
The August jobs report delivered a sharp counterpoint to recent signs of labor-market weakness. Employers added 162,000 jobs, compared with economists' expectations for 55,000, while the unemployment rate held at 4.1%. June and July payrolls were also revised higher by a combined 55,000 jobs.
For markets, however, stronger employment created a complication. With the labor market holding up and inflation still above the Federal Reserve's 2% target, traders increased expectations for a September rate hike. At the same time, Trump intensified his campaign for lower rates, arguing that a stronger U.S. economy should mean cheaper borrowing and threatening to stop trade with countries running surpluses with the United States.
Key Points
- U.S. employers added 162,000 jobs in August versus 55,000 expected, while unemployment remained at 4.1% and labor-force participation rose to 61.6%.
- The strong report increased expectations for a September Fed rate hike, with market-implied odds moving to roughly 60% as investors turned their attention to next week's inflation data.
- Trump demanded lower interest rates despite the strong employment report and threatened to halt trade with countries where the U.S. runs deficits, adding trade-policy uncertainty to the rate outlook.
August Jobs Report Signals a More Resilient Labor Market
The headline payroll number was substantially stronger than economists expected, but several details underneath it also pointed to improving labor conditions.
Labor-force participation increased to 61.6%, helped by a 300,000 increase in people moving directly from the sidelines into employment. That additional labor supply helped keep unemployment at 4.1% even as more people entered the workforce.
Underemployment improved as well. The number of people working part time for economic reasons declined by 414,000 to 4.4 million, while the broadest measure of labor underutilization fell to 7.7%, its lowest level of the year.
Hiring was widespread but uneven. Food services added 59,000 jobs, while local government education added 42,000. Construction gained 22,000 positions, and healthcare added 13,000. The information sector lost 23,000 jobs and finance shed 11,000.
Wages provided a more moderate signal. Average hourly earnings increased 0.3% from July and 3.1% from a year earlier, a pace described in the provided material as consistent with the Fed's 2% inflation objective.
The report also reversed some of the weakness previously visible in the data. June and July payroll figures were revised upward by a combined 55,000 jobs, including a revision that moved July from an initially reported loss back into positive territory.
The numbers are not necessarily definitive. Labor-market data have been volatile over the summer, and Raymond James Chief Economist Eugenio Aleman said there is a high probability August employment growth will eventually be revised lower, while remaining positive.
Even with that caveat, the report left little evidence of an immediate deterioration in employment that would force the Fed to prioritize the labor side of its dual mandate.
Why Did Strong Jobs Increase the Chances of a Fed Rate Hike?
The market reaction reflected a familiar tension: economic strength can be positive for the economy while simultaneously reducing the case for easier monetary policy.
Fed Chairman Kevin Warsh had already signaled concern about inflation, which has remained above the central bank's 2% target for 5½ years. He said last week that he needed confidence inflation was returning to target "clearly and at sufficient speed," adding that otherwise the Fed still had work to do.
The August employment report strengthened the labor-market side of the case for tightening. Rather than providing evidence that higher rates were causing serious employment deterioration, the report showed stronger hiring, steady unemployment, rising participation and lower underemployment.
Markets responded accordingly. The probability of a 25-basis-point September rate increase moved to around 60%, compared with roughly 50% on Thursday. Later estimates cited in the provided material put the probability near 62%.
Some economists also changed their forecasts. UBS moved its expected first 25-basis-point hike to September and projected another in December, while Macquarie shifted its expected first hike from December to September and continued to anticipate another increase in the first quarter of 2027. Nationwide Chief Economist Kathy Bostjancic said she expected two quarter-point hikes by year-end, taking the federal funds rate to 4%–4.25%.
The decision is not settled. Fed Governor Christopher Waller said he would lean toward keeping rates unchanged in the current 3.50%–3.75% range if upcoming inflation reports show price pressures continuing to moderate.
That makes next week's inflation data particularly important. August consumer inflation is due September 11, while producer-price data will also arrive before the Fed meeting. Several economists cited in the provided material described those reports as more consequential for the September decision than the employment report itself.
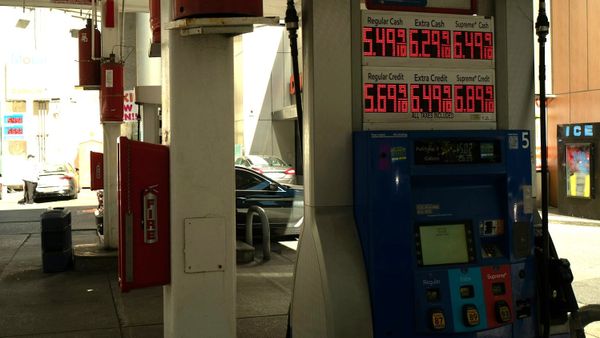
Another inflationary complication is emerging from energy. U.S. retail diesel reached a record $5.85 per gallon Friday. Diesel is central to freight and goods transportation, meaning higher prices can move through supply chains. U.S. distillate inventories are also at record lows for this time of year, while geopolitical disruptions have constrained global supplies.
The combination leaves the Fed confronting an economy in which employment remains resilient while inflation risks have not disappeared.
Trump's Rate Demands Add a Trade-Policy Risk
The strong employment report produced almost the opposite policy conclusion from Trump.
Trump called the jobs number "great," but argued that the stronger economy should result in lower interest rates. He wrote that a "STRONG COUNTRY MEANS A LOWER INTEREST RATE" and said high rates put the United States at an unfair disadvantage.
That position differs from the monetary-policy implications markets drew from Friday's employment report. With inflation above target, stronger economic activity gives the Fed more room to maintain or tighten monetary policy rather than reducing rates to support employment.
Trump went further by connecting monetary policy to trade.
"LOWER THE RATE OR I'LL STOP TRADING WITH COUNTRIES WITH WHICH WE HAVE A DEFICIT," he wrote, later suggesting an embargo could be "BETTER THAN TARIFFS." Speaking to reporters, Trump also floated banning trade with Canada and criticized U.S. trade deficits with Mexico and the European Union.
The U.S. goods and services trade deficit widened 24.4% in July to $88.6 billion from $71.2 billion in June. The country ran deficits with several major partners, including Mexico, Vietnam, China and the European Union.
Part of the increase, however, was connected to investment spending. Computer imports increased 25% between June and July, while semiconductor imports rose 10% as technology companies continued investing in AI infrastructure. Construction employment, which includes jobs associated with data-center development, increased by 22,000 in August.
An embargo would also represent a substantially different policy instrument from a tariff. Rather than making imported products more expensive, an embargo can stop trade altogether. The provided material notes that such action against major trading partners could disrupt supply chains, reduce product availability and raise prices.
That creates another potential tension with the demand for lower interest rates: trade restrictions that increase prices could add to inflation pressure at a time when the Fed is deciding whether inflation is cooling quickly enough to avoid another rate increase.
The political pressure also complicates Warsh's position. Raising rates after Trump's public demands could invite presidential criticism. Holding rates steady after Warsh's recent hawkish comments could instead raise questions about the consistency of the Fed's policy response.
The final decision will therefore arrive at the intersection of employment strength, inflation data and unusually visible political pressure on the central bank.
What It Means for Investors
Friday's stock market reaction showed why a strong economic report does not always translate into higher equity prices.
The Dow Jones Industrial Average finished down about 0.5%, the S&P 500 declined roughly 0.4%, and the Nasdaq Composite slipped about 0.3%. The two-year Treasury yield, which is particularly sensitive to expectations for near-term monetary policy, moved higher after the jobs report. The dollar also strengthened.
The chain of events was relatively direct: stronger-than-expected hiring reduced concerns about labor-market weakness, which increased expectations that the Fed has room to concentrate on inflation. That pushed rate-hike probabilities higher and weighed on equities.
Other assets reflected the same repricing. Bitcoin reversed after approaching $83,000 and fell below $80,000, while gold also moved lower as short-term yields and the dollar increased.
Inflation is now the critical next piece of the policy picture. A strong labor market gives the Fed less reason to avoid tightening because of employment concerns, but Fed officials have indicated that incoming inflation data will play the larger role in determining whether rates actually rise in September.
Trump's trade threats introduce a separate source of uncertainty. The immediate issue for markets is not whether every threatened embargo will occur, but that trade policy has become intertwined with the president's campaign for lower interest rates at the same time the economic data are pushing market expectations toward tighter monetary policy.
That leaves investors facing three connected variables heading into the Fed meeting: resilient employment, persistent inflation risk and increased uncertainty surrounding U.S. trade policy.
Conclusion
The August jobs report materially changed the backdrop for the Federal Reserve's September decision.
Payroll growth of 162,000 nearly tripled expectations, unemployment remained at 4.1%, participation increased and previous months were revised higher. The report did not settle the Fed debate, but it removed some of the labor-market justification for avoiding another rate increase.
Attention now shifts to August inflation data. If price pressures remain elevated, the combination of persistent inflation and resilient employment would reinforce the case for tighter policy described by Warsh. If inflation shows sufficient improvement, officials including Waller have indicated they could support keeping rates unchanged.
Trump is pushing in precisely the opposite direction, demanding lower rates and escalating that demand with threats against U.S. trading partners.
For markets, the resulting tension explains Friday's seemingly counterintuitive reaction: the jobs report was strong for the economy, but it increased the perceived probability of higher interest rates while new trade threats added another layer of policy uncertainty.
FAQs
How many jobs did the U.S. add in August?
U.S. employers added 162,000 jobs in August, nearly three times the 55,000 increase economists had expected. The unemployment rate remained at 4.1%, while June and July payrolls were revised higher by a combined 55,000 jobs.
Why did the strong jobs report increase expectations for a Fed rate hike?
The report showed resilient employment, steady unemployment, rising labor-force participation and lower underemployment. With inflation still above the Fed's 2% target, the stronger labor market gives policymakers more room to focus on price stability rather than supporting employment.
What will determine whether the Fed raises rates in September?
The August CPI and PPI inflation reports are expected to be key inputs before the Fed meeting. Chairman Kevin Warsh has indicated that inflation needs to move toward the 2% target clearly and sufficiently quickly, while Governor Christopher Waller has said improving inflation data could support leaving rates unchanged.
What did Trump say about interest rates and trade?
Trump demanded lower interest rates and wrote, "LOWER THE RATE OR I'LL STOP TRADING WITH COUNTRIES WITH WHICH WE HAVE A DEFICIT." He later discussed potential embargoes and specifically raised the possibility of stopping trade with Canada.
Why did stocks fall after a strong jobs report?
The strong employment numbers increased expectations for a September Fed rate hike. Short-term Treasury yields and the dollar moved higher, while the Dow, S&P 500 and Nasdaq declined as markets adjusted to the possibility of tighter monetary policy.
This article was created with AI assistance and reviewed by an editor. For details, please refer to our Terms of Use.
Go Beyond the Market Brief with Market Edge
Follow SharperTrades’ complete approach to trading and investing, combining active trade opportunities through Block Orders, long-term research through Stock Investor, and structured market education through the Swing Trading Masterclass. Try Market Edge for $19 your first month →
Explore Research with Stock Investor
Stock Investor is SharperTrades’ platform for long-term investing research and portfolio management. Members receive research reports, portfolio updates, conviction tracking, and in-depth analysis designed to support disciplined investment decisions.
Explore Active Trading & Income Strategies
Block Orders tracks institutional activity and highlights active trade setups and price behavior across long and short opportunities.
For options-focused traders, Essential Option Income provides a structured approach to options income strategies, while Pro Option Trader offers a broader range of options strategies and trade opportunities.
Think More Clearly with SteadyCapital
SteadyCapital is SharperTrades’ decision-support system for long-term investors, built around the SteadyCapital Method™. Review investment ideas, challenge assumptions, evaluate valuation and risk, compare companies, and think through important buy, hold, add, trim, or sell decisions before you act.
Risk Disclosure
All content is provided for educational purposes only and does not constitute investment advice. Trading involves risk, and past performance is not indicative of future results. Please review our full Risk Disclosure for additional information.