Intuitive Surgical Faces Pricing Pressure Despite Strong Earnings
Intuitive Surgical (ISRG) shares declined despite strong third-quarter earnings as slower U.S. procedure growth and planned instrument price reductions raised concerns about future revenue. International expansion and robotic system demand remained strong.
Strong Earnings Overshadowed by Slower U.S. Growth and Pricing Changes
Intuitive Surgical (ISRG) shares declined on Wednesday, October 21, after the robotic surgery company reported stronger-than-expected third-quarter results but outlined pricing changes that could affect future revenue growth.
The stock fell nearly 8% in premarket trading before recovering part of those losses, trading approximately 3% lower later in the session. Investors focused on slowing U.S. surgical procedure growth, planned reductions in instrument pricing, and a $450 million antitrust settlement.
Key Points
- Intuitive Surgical exceeded third-quarter revenue and adjusted earnings expectations, supported by robotic system placements and recurring instrument sales.
- U.S. da Vinci procedure growth slowed to 10%, while planned pricing changes could reduce instrument revenue per procedure by 3%–5%.
- International expansion and new robotic systems remain growth opportunities, but competition and profitability pressures are drawing greater attention.
Intuitive Surgical Earnings Show Strong Revenue and System Demand
Intuitive Surgical reported third-quarter revenue of $3.05 billion, increasing 22% year over year and exceeding Wall Street expectations of approximately $2.91 billion.
Adjusted earnings reached $3.00 per share, compared with analyst estimates of roughly $2.65.
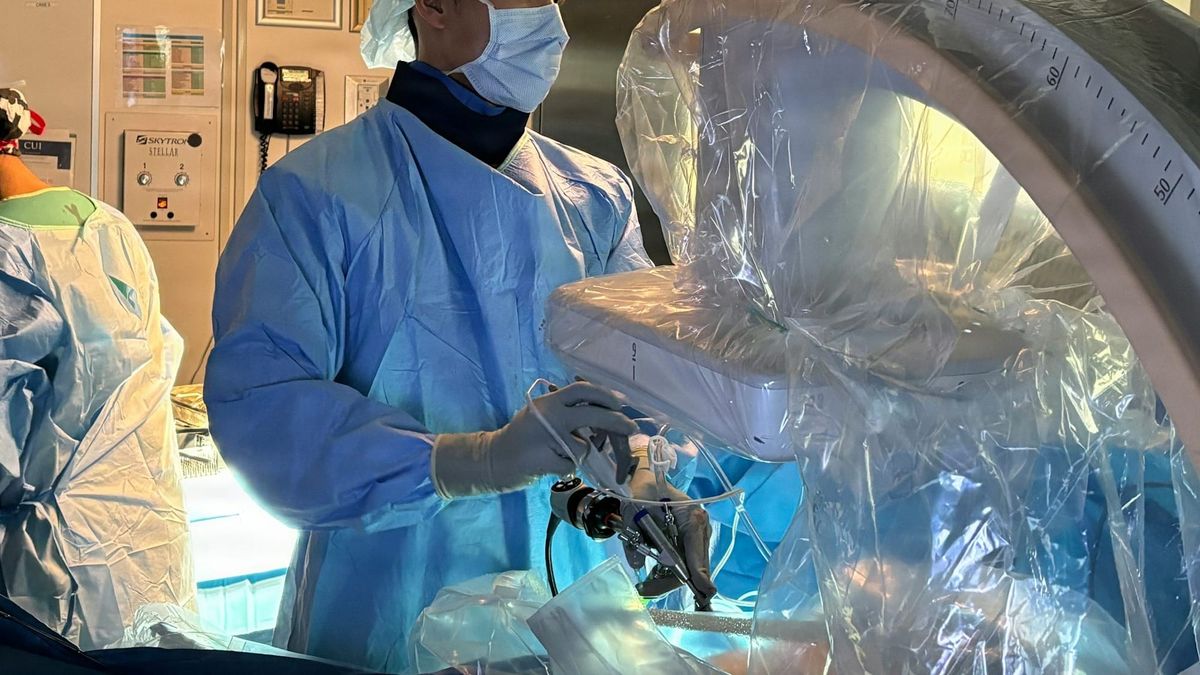
The company benefited from continued adoption of its da Vinci robotic surgery systems, which allow surgeons to perform minimally invasive procedures using robotic instruments controlled from a nearby console.
Intuitive placed 546 da Vinci systems during the quarter, an increase of 28% from the previous year.
Instruments and accessories revenue also rose 18% to approximately $1.8 billion, supported by higher surgical procedure volumes.
These recurring sales are an important part of Intuitive's business model. Hospitals purchase or lease robotic systems and subsequently generate ongoing demand for instruments, accessories, and maintenance services as procedures are performed.
Recurring revenue accounted for approximately 84% of total revenue during the quarter.
International Procedures Outpace U.S. Growth
Worldwide da Vinci procedure volumes increased approximately 14%, but growth varied significantly by region.
U.S. procedures increased 10% year over year, compared with 20% growth internationally.
The domestic performance represented one of the company's slowest growth rates in recent years. Management partly attributed the slowdown to a difficult comparison with the previous year, when U.S. procedures increased 16%.
Intuitive narrowed its full-year 2026 worldwide procedure growth forecast to 14%–15%, compared with its previous range of 13.5%–15.5%.
The midpoint remained unchanged, indicating that management's overall expectations had not materially improved despite stronger equipment placements.
The company's Ion platform, designed for minimally invasive lung biopsies, continued expanding, with procedures increasing 31%.
Why Did Intuitive Surgical Stock Fall Despite Strong Earnings?
The market's negative reaction centered on future pricing rather than current sales performance.
Management expects changes to its instrument and accessory pricing structure to reduce revenue generated per da Vinci procedure by approximately 3%–5% once fully implemented.
The adjustments include extended-use instruments, volume-based pricing arrangements, and price reductions in China.
Extended-use instruments can be used for more procedures before requiring replacement, potentially reducing the amount hospitals spend on instruments for each surgery.
China's pricing changes are expected to begin in November, while the broader adjustments will continue through 2027.
Lower Revenue per Procedure Creates a Growth Challenge
Because instruments and accessories represent a major recurring revenue source, lower revenue per procedure could affect sales growth even if surgical volumes continue increasing.
The eventual financial impact will depend on procedure growth, product mix, and whether lower pricing encourages additional adoption.
The timing is particularly relevant: pricing reductions may affect revenue before any resulting increase in surgical volumes becomes apparent.
Investors are also assessing Intuitive's ability to maintain profitability while expanding its technology and supporting hospital adoption.
Third-quarter adjusted gross margin reached 69.9%, partly benefiting from a $28 million tariff refund. Management raised its full-year gross margin outlook but reiterated its broader operating margin framework of 35%–40%.
Antitrust Settlement Adds to the Reaction
Intuitive also disclosed a $450 million settlement related to antitrust litigation involving its da Vinci instruments.
The lawsuit, filed in 2021, accused the company of anticompetitive practices involving instrument servicing and repairs.
Intuitive agreed to the settlement without admitting wrongdoing, and the agreement remains subject to court approval.
The charge reduced reported earnings under generally accepted accounting principles (GAAP) to $1.49 per share, compared with adjusted earnings of $3.00.
While the settlement affected reported profitability, the pricing outlook and slower domestic procedure growth introduced more persistent questions about future operating performance.
What Comes Next for Intuitive Surgical?
Intuitive's outlook depends partly on whether international procedure growth and expanding robotic system adoption can offset lower instrument revenue per procedure.
The company continues to benefit from demand for its da Vinci platform, including newer systems such as da Vinci 5 and expanding single-port surgical procedures.
However, the competitive environment is evolving.
Johnson & Johnson (JNJ) received regulatory approval for its Ottava soft-tissue robotic surgery system in July, positioning it as a potential competitor to da Vinci.
Medtronic (MDT) also received regulatory clearance for its Hugo robotic system in urological procedures in December 2025.
These developments introduce additional competition into a market where Intuitive has maintained a leading position for decades.
Pricing Rollout and Healthcare Policy Remain Important
The transition to extended-use instruments and revised pricing agreements could create temporary changes in hospital purchasing patterns as customers adjust their inventory.
U.S. healthcare policy is another consideration. Analysts have identified uncertainty surrounding Affordable Care Act enrollment, Medicaid eligibility, and hospital reimbursement programs as potential influences on surgical volumes.
Intuitive's international operations provide a different growth profile, although China's policy-driven pricing reductions introduce additional pressure in that market.
The 2027 Outlook Will Provide Greater Clarity
Management's next major financial outlook, expected in January, will provide additional information about spending priorities and operating expectations for 2027.
Future quarterly results will also show how the pricing changes affect recurring revenue and whether procedure volumes continue expanding.
For now, the central unresolved issue is how quickly additional surgical activity can compensate for lower revenue generated from each procedure.
What It Means for Investors
Intuitive Surgical's earnings reaction reflects the importance of recurring revenue economics in the medical technology industry.
The company continues to sell more robotic systems and support a growing volume of procedures. However, lower instrument revenue per procedure could moderate the financial benefits of that expansion.
Its established installed base provides recurring demand, while international markets offer opportunities for further adoption. At the same time, pricing adjustments and emerging competition introduce uncertainty around future margins.
For investors following ISRG stock, procedure growth alone may no longer provide a complete picture. The relationship between surgical volumes, revenue per procedure, and operating profitability has become increasingly important.
Conclusion
Intuitive Surgical delivered strong quarterly earnings and continued expanding its robotic surgery business, but investors responded cautiously to changes affecting its future revenue model.
Slower U.S. procedure growth and planned instrument pricing reductions raised questions about how effectively the company can translate higher surgical volumes into earnings growth.
International demand and new robotic systems remain important opportunities, while competition and healthcare policy introduce additional considerations.
The upcoming 2027 outlook will help clarify how management expects to balance growth, pricing, and profitability.
FAQs
Why did Intuitive Surgical stock fall after its earnings report?
Intuitive Surgical stock declined because investors focused on slower U.S. procedure growth, planned reductions in instrument revenue per procedure, and a $450 million antitrust settlement despite stronger-than-expected earnings.
Did Intuitive Surgical beat third-quarter earnings expectations?
Yes. Intuitive Surgical reported adjusted earnings of $3.00 per share, above estimates of approximately $2.65. Revenue reached $3.05 billion, exceeding expectations of roughly $2.91 billion.
Why is Intuitive Surgical reducing instrument revenue per procedure?
Intuitive Surgical expects extended-use instruments, volume-based pricing arrangements, and price reductions in China to lower revenue per procedure by approximately 3%–5% once fully implemented.
How fast are da Vinci surgical procedures growing?
Worldwide da Vinci procedures increased approximately 14% in the third quarter. U.S. procedures grew 10%, while international procedures increased 20%.
What should investors watch next for Intuitive Surgical?
Important developments include the rollout of instrument pricing changes, surgical procedure growth, emerging competition, and the company's expected January outlook for 2027.
This article was created with AI assistance and reviewed by an editor. For details, please refer to our Terms of Use.
Go Beyond the Market Brief with Market Edge
Follow SharperTrades’ complete approach to trading and investing, combining active trade opportunities through Block Orders, long-term research through Stock Investor, and structured market education through the Swing Trading Masterclass. Try Market Edge for $19 your first month →
Explore Research with Stock Investor
Stock Investor is SharperTrades’ platform for long-term investing research and portfolio management. Members receive research reports, portfolio updates, conviction tracking, and in-depth analysis designed to support disciplined investment decisions.
Explore Active Trading & Income Strategies
Block Orders tracks institutional activity and highlights active trade setups and price behavior across long and short opportunities.
For options-focused traders, Essential Option Income provides a structured approach to options income strategies, while Pro Option Trader offers a broader range of options strategies and trade opportunities.
Think More Clearly with SteadyCapital
SteadyCapital is SharperTrades’ decision-support system for long-term investors, built around the SteadyCapital Method™. Review investment ideas, challenge assumptions, evaluate valuation and risk, compare companies, and think through important buy, hold, add, trim, or sell decisions before you act.
Risk Disclosure
All content is provided for educational purposes only and does not constitute investment advice. Trading involves risk, and past performance is not indicative of future results. Please review our full Risk Disclosure for additional information.