Levi Strauss Profit Boost Masks Slower Direct-to-Consumer Growth
Levi Strauss raised its full-year earnings outlook after tariff refunds lifted quarterly profits. But weaker direct-to-consumer sales, a slight revenue miss and changing denim preferences weighed on investor sentiment, sending shares lower despite strength in wholesale and international markets.
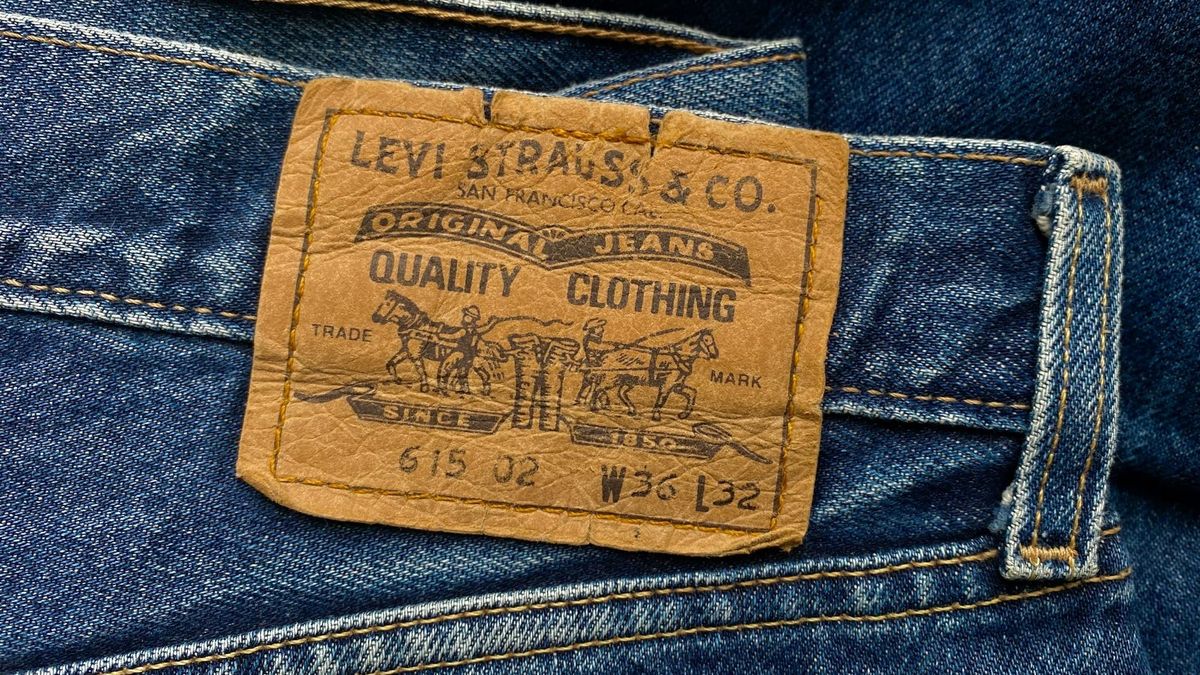
Levi Strauss Raises Guidance, but Retail Weakness Pressures Shares
Levi Strauss & Co. (LEVI) reported mixed fiscal third-quarter results, with adjusted earnings reaching $0.48 per share, exceeding Wall Street expectations, while revenue increased 4% to $1.61 billion, slightly below estimates. The company also raised its full-year profit outlook, benefiting significantly from refunds on previously paid tariffs.
However, LEVI stock declined approximately 3% following the report as investors focused on slowing direct-to-consumer sales and the temporary nature of much of the earnings improvement. While international and wholesale operations remained strong, weaker store traffic in the United States and Europe highlighted challenges in the company's retail strategy.
Key Points
- Levi Strauss exceeded quarterly earnings expectations and raised its full-year profit outlook, although tariff refunds accounted for a substantial portion of the improvement.
- Direct-to-consumer growth slowed sharply as weaker traffic and a missed shift in denim preferences weighed on U.S. and European sales.
- Wholesale and international operations remained strong, while management expects retail momentum to improve during the fourth quarter.
Why Did Levi Strauss Stock Fall Despite Stronger Earnings?
Levi Strauss reported adjusted quarterly earnings of $0.48 per share, well above the $0.36 analysts expected and higher than the $0.34 recorded a year earlier.
However, the headline earnings improvement was significantly influenced by tariff refunds.
The company received $79 million in refunds on previously paid tariffs, reducing its cost of goods sold and boosting profitability. After reinvesting part of those benefits into marketing and other initiatives, the refunds contributed approximately $0.11 per share to adjusted earnings.
Excluding that benefit, quarterly earnings would have been approximately $0.37 per share, reflecting a much more modest improvement from the previous year.
Gross margin, which measures the portion of sales remaining after product costs, expanded substantially. Yet most of that improvement also reflected the tariff refunds rather than underlying operating gains.
Revenue presented another concern.
Quarterly sales increased 4%, but growth slowed from the previous quarter and narrowly missed Wall Street expectations.
The combination of slower revenue growth, weaker direct-to-consumer performance and refund-supported profitability helps explain why investors reacted negatively despite the earnings beat and higher guidance.
Direct-to-Consumer Slowdown Exposes a Denim Trend Misstep
The most significant operational disappointment came from Levi Strauss' direct-to-consumer business, which includes company-operated stores and online sales.
DTC revenue increased just 2%, slowing from stronger growth in the previous quarter. Comparable sales were essentially flat, while revenue declined in both the United States and Europe.
Management attributed part of the weakness to an unsuccessful back-to-school campaign.
Levi Strauss had emphasized baggy denim silhouettes in its U.S. marketing and merchandising strategy, but consumer preferences shifted toward low-rise styles.
CEO Michelle Gass acknowledged the mismatch and said the company moved quickly to redirect marketing and product support toward stronger-selling trends.
Unusually warm weather also affected European store traffic.
Despite these challenges, the broader business showed resilience.
Wholesale revenue increased 6%, supported by demand across multiple regions. International organic revenue grew 8%, with Asia delivering particularly strong results.
The company's expansion beyond traditional denim bottoms also continued to gain traction. Tops revenue increased 7%, while women's apparel and lifestyle categories contributed to overall growth.
These results suggest that the weakness was concentrated in specific retail channels and merchandising decisions rather than affecting every part of the business.
Can Levi Strauss Restore Retail Momentum in the Holiday Quarter?
Levi Strauss expects its direct-to-consumer business to return to mid-single-digit growth in the fourth quarter.
Management reported improving U.S. retail trends in September following changes to marketing and product assortments. European performance also improved as temperatures cooled.
The company is maintaining its broader strategy of expanding direct consumer relationships while diversifying beyond jeans into tops, dresses and other lifestyle categories.
For fiscal 2026, Levi Strauss raised its adjusted earnings guidance to $1.54–$1.56 per share, compared with its previous forecast of $1.46–$1.52.
However, the revised outlook includes the benefit of tariff refunds, limiting how much of the increase reflects stronger underlying operations.
The company also narrowed its full-year reported revenue growth expectation to approximately 7%, while maintaining organic growth guidance near 6%.
In addition, Levi Strauss announced plans for a $100 million accelerated share repurchase program and increased its quarterly dividend to $0.16 per share.
The next quarter will provide an important measure of whether management's merchandising adjustments and improving retail trends can support a more consistent recovery in direct-to-consumer sales.
What It Means for Investors
Levi Strauss' earnings report highlights the importance of distinguishing temporary financial benefits from sustainable operating improvements.
The company delivered stronger profitability and raised its earnings outlook, but tariff refunds accounted for a meaningful portion of both developments.
At the same time, its direct-to-consumer business—an important part of the company's growth and margin strategy—experienced a notable slowdown.
The negative reaction in LEVI stock reflects these concerns, particularly after shares had already retreated substantially from their summer highs.
There were also encouraging developments.
Wholesale demand remained healthy, international markets continued expanding, and product categories beyond denim bottoms contributed to growth.
For investors, the next indicators are direct-to-consumer comparable sales, retail traffic, product assortment performance and underlying margins excluding tariff-related benefits.
The company's ability to sustain its September improvement through the holiday shopping season will be particularly relevant.
Conclusion
Levi Strauss delivered stronger quarterly earnings and raised its full-year profit forecast, but the results revealed a more complicated operating picture.
Tariff refunds provided a substantial boost to profitability, while direct-to-consumer sales slowed and revenue narrowly missed expectations.
Strength in wholesale, international markets and lifestyle categories helped offset some of that weakness.
Management has already adjusted its merchandising and marketing strategy in response to changing denim preferences, with early signs of improvement entering the fourth quarter.
The central question is whether those adjustments can restore consistent retail growth and strengthen profitability beyond the temporary benefits of tariff refunds.
FAQs
Why did Levi Strauss stock fall after its earnings report?
Levi Strauss shares declined approximately 3% as investors focused on weaker direct-to-consumer sales, a slight revenue miss and the significant contribution of tariff refunds to reported earnings.
How much did tariff refunds contribute to Levi Strauss' earnings?
Tariff refunds contributed approximately $0.11 per share to adjusted third-quarter earnings after reinvestments. Excluding that benefit, adjusted earnings would have been approximately $0.37 per share.
Why did Levi Strauss' direct-to-consumer sales slow?
Direct-to-consumer sales slowed because of weaker traffic in the United States and Europe, an underperforming back-to-school campaign and a shift in consumer demand toward low-rise denim styles.
What is Levi Strauss' updated earnings outlook for 2026?
Levi Strauss raised its fiscal 2026 adjusted earnings guidance to $1.54–$1.56 per share, compared with its previous forecast of $1.46–$1.52. The updated outlook includes tariff-refund benefits.
What should investors watch next for LEVI stock?
Investors are watching direct-to-consumer sales growth, retail traffic, holiday-season demand and underlying operating margins to assess whether Levi Strauss can sustain its retail recovery.
This article was created with AI assistance and reviewed by an editor. For details, please refer to our Terms of Use.
Go Beyond the Market Brief with Market Edge
Follow SharperTrades’ complete approach to trading and investing, combining active trade opportunities through Block Orders, long-term research through Stock Investor, and structured market education through the Swing Trading Masterclass. Try Market Edge for $19 your first month →
Explore Research with Stock Investor
Stock Investor is SharperTrades’ platform for long-term investing research and portfolio management. Members receive research reports, portfolio updates, conviction tracking, and in-depth analysis designed to support disciplined investment decisions.
Explore Active Trading & Income Strategies
Block Orders tracks institutional activity and highlights active trade setups and price behavior across long and short opportunities.
For options-focused traders, Essential Option Income provides a structured approach to options income strategies, while Pro Option Trader offers a broader range of options strategies and trade opportunities.
Think More Clearly with SteadyCapital
SteadyCapital is SharperTrades’ decision-support system for long-term investors, built around the SteadyCapital Method™. Review investment ideas, challenge assumptions, evaluate valuation and risk, compare companies, and think through important buy, hold, add, trim, or sell decisions before you act.
Risk Disclosure
All content is provided for educational purposes only and does not constitute investment advice. Trading involves risk, and past performance is not indicative of future results. Please review our full Risk Disclosure for additional information.