Boeing’s Record $745 Billion Backlog Highlights the Challenge of Turning Demand Into Profit
Boeing narrowed its third-quarter loss and generated positive free cash flow, but commercial aircraft losses, production constraints, and a one-time defense gain weighed on its recovery despite a record $745 billion backlog.
Boeing’s Recovery Advances, but Commercial Aircraft Profitability Remains Elusive
Boeing (BA) reported a sharply narrower third-quarter loss as revenue increased 4% to $24.19 billion and its total order backlog reached a record $745 billion. The aerospace manufacturer also generated $464 million in free cash flow, exceeding Wall Street expectations and marking further progress in its financial recovery.
However, the results revealed continuing challenges in Boeing's commercial aircraft business. A larger-than-expected divisional loss, higher supply-chain costs, and production constraints overshadowed improvements elsewhere. Boeing shares fell approximately 1.8% following the report, reflecting investor concerns about how quickly the company can translate its substantial order backlog into sustainable profitability.
Key Points
- Financial recovery continues: Boeing narrowed its quarterly net loss to $116 million from $5.34 billion a year earlier, while free cash flow reached $464 million and its backlog climbed to a record $745 billion.
- Commercial aircraft remain the primary obstacle: The division lost $697 million despite delivering 161 aircraft, as unfavorable delivery mix, production-adjustment costs, and supply-chain pressures weighed on margins.
- Defense and services provided support: Both divisions reported stronger operating profits, although a $252 million asset-sale gain accounted for more than half of defense operating earnings.
Boeing Narrows Its Loss, but Earnings Fall Short of Expectations
Boeing's third-quarter results showed substantial improvement from the prior year, when the company was dealing with significant production challenges and charges associated with its 777X aircraft program.
The manufacturer reported a net loss of $116 million, compared with $5.34 billion a year earlier. Revenue increased to $24.19 billion, while operating income reached $354 million, reversing a $4.78 billion operating loss in the comparable period.
Nevertheless, Boeing's adjusted loss of $0.34 per share was wider than analysts expected. Revenue was broadly in line with or ahead of expectations, depending on the consensus estimate used.
Cash generation offered a more encouraging development. Operating cash flow reached $1.50 billion, while free cash flow totaled $464 million, exceeding analyst forecasts.
Free cash flow represents the cash remaining after capital expenditures and is particularly important for Boeing because it indicates how much financial flexibility the company has to support production, fund development, and eventually reduce debt.
Still, the improvement requires context. Working-capital timing contributed to quarterly cash generation, and free cash flow remained negative $359 million for the first nine months of 2026.
Boeing ended September with $20.7 billion in cash and marketable securities and $45.9 billion in debt, highlighting the importance of sustaining positive cash generation beyond an individual quarter.
Why Did Boeing Stock Fall Despite Improving Financial Results?
The market's reaction reflected the difference between improving companywide results and the profitability challenges still facing Boeing's largest manufacturing operation.
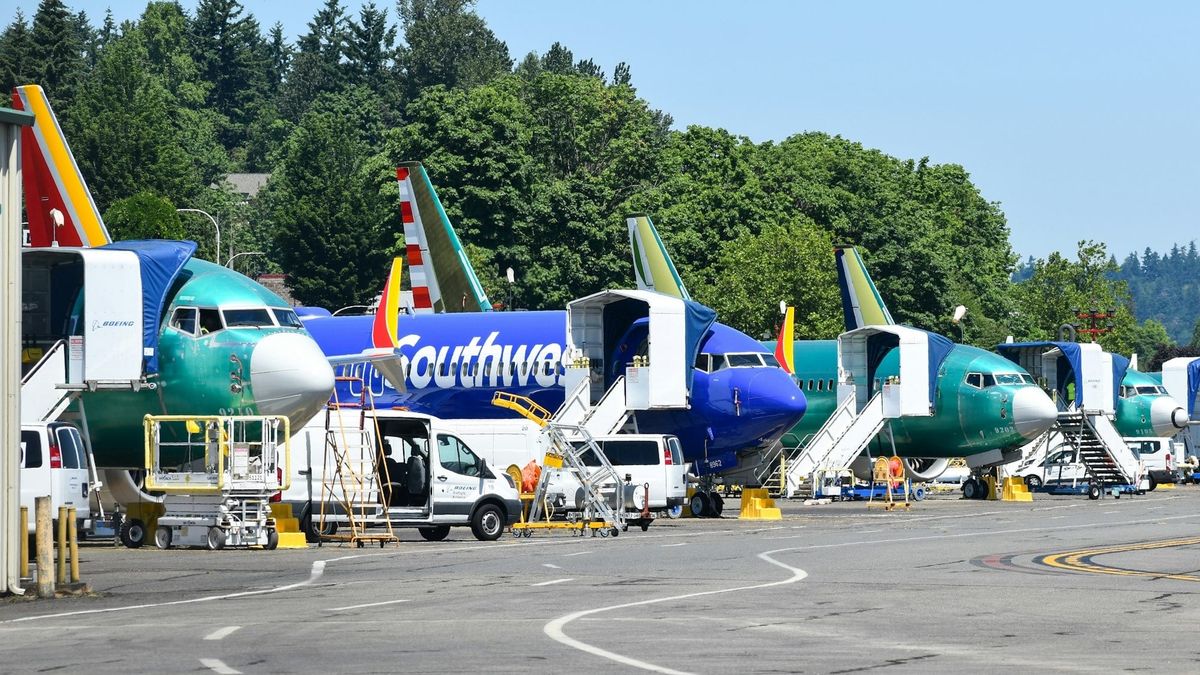
Commercial Airplanes revenue declined 3% to $10.72 billion, even as quarterly deliveries edged higher to 161 aircraft from 160 a year earlier.
The division reported a $697 million operating loss, significantly worse than the approximately $361 million deficit analysts had anticipated.
Boeing attributed the pressure to an unfavorable delivery mix, higher estimated supply-chain costs, and projected expenses associated with future production-rate adjustments.
These results highlight a central challenge: delivering more aircraft does not automatically translate into higher profitability when production costs and the mix of aircraft delivered remain unfavorable.
The contrast was particularly noticeable in Boeing's defense business.
Defense, Space & Security revenue increased 15% to $7.94 billion, while operating profit rose to $492 million from $114 million a year earlier.
However, approximately $252 million of that profit came from the sale of HRL Laboratories. Excluding the gain, defense operating profit would have been roughly $240 million, implying a margin of approximately 3%, compared with the reported 6.2%.
The distinction matters because gains from asset sales do not represent recurring earnings from aircraft manufacturing or defense programs.
Global Services provided a more consistent source of operating profitability. Revenue increased 4% to $5.57 billion, while operating profit rose 9% to $1.02 billion. Its operating margin expanded to 18.3%, supported by favorable business volume and mix.
Together, these results explain why investors remained cautious despite the sharp reduction in Boeing's consolidated loss.
The company is demonstrating financial improvement, but its commercial aircraft division has yet to return to sustained operating profitability.
Can Boeing Convert Its Record Backlog Into Sustainable Earnings?
Boeing's record $745 billion backlog underscores the scale of demand for its aircraft, defense programs, and services.
Commercial aircraft accounted for approximately $612 billion of that total, representing more than 6,300 airplanes awaiting delivery. Defense contributed approximately $101 billion, while Global Services accounted for roughly $33 billion.
The company also recorded 300 net commercial aircraft orders during the third quarter.
However, an order backlog represents contracted future business rather than revenue already earned. Boeing must manufacture, deliver, and receive payment for aircraft before much of that demand can translate into operating cash flow.
Production capacity and execution therefore remain central to its recovery.
Boeing is working toward stabilizing 737 production at 47 aircraft per month, while 787 Dreamliner production remains at eight per month.
Engine delivery constraints have complicated efforts to increase output, particularly as the company attempts to expand production while maintaining quality and operational discipline.
There have also been important program milestones.
The Federal Aviation Administration certified the 737-7 and 737-10 variants, removing significant regulatory obstacles to future deliveries of those aircraft.
Meanwhile, Boeing was selected to design and build the U.S. Navy's next-generation F/A-XX fighter aircraft, although that award has not yet been incorporated into its reported backlog.
The delayed 777-9 widebody aircraft remains another major priority, with first delivery targeted for 2027.
CEO Kelly Ortberg emphasized that recent certifications and the Navy contract represent progress, while reiterating the company's focus on safety, quality, and disciplined execution.
For Boeing, the next stage of recovery depends less on demonstrating demand and more on converting that demand into reliable production, deliveries, and recurring earnings.
What It Means for Investors
Boeing's third-quarter results illustrate a company making measurable financial progress while still facing substantial operational challenges.
The sharp reduction in losses, positive quarterly free cash flow, and expanding backlog indicate improvement from the difficulties experienced in previous years.
However, the commercial aircraft business remains the central variable in Boeing's financial recovery.
Higher delivery volumes will matter most when accompanied by better margins, more predictable production costs, and sustained cash generation.
Investors also need to distinguish between recurring operating performance and temporary financial benefits. The HRL Laboratories asset-sale gain supported reported defense earnings, while working-capital timing contributed to quarterly cash flow.
Neither development, by itself, establishes that Boeing has reached a sustainable level of profitability.
The company's substantial debt adds another consideration. Although liquidity remains significant, consistent free cash flow will be important for improving its financial position over time.
Market sentiment has also been mixed. Boeing shares declined approximately 13% from the end of the second quarter entering earnings week, despite the proportion of analysts rating the stock Buy increasing to 85% from 77% at the end of June.
That divergence reflects the tension between expectations for a longer-term turnaround and the operational difficulties still visible in current results.
For investors following BA stock, the most relevant indicators remain commercial aircraft margins, production stability, free cash flow, and progress toward the 777-9 delivery schedule.
Conclusion
Boeing's third-quarter report showed meaningful progress in its financial recovery, including sharply reduced losses, positive cash generation, and a record order backlog.
Yet the results also demonstrated why the turnaround remains incomplete.
Commercial aircraft losses continue to weigh on profitability, while production constraints and supply-chain expenses limit the financial benefits of strong demand.
Defense and services are contributing to improved results, but one-time gains complicate the assessment of underlying earnings strength.
Boeing's challenge is now to translate its substantial backlog and recent program milestones into sustained operating performance.
The company's progress toward higher production rates, improved commercial margins, and consistent free cash flow will provide the clearest evidence of whether its recovery is becoming more durable.
FAQs
Why did Boeing stock decline after its third-quarter earnings report?
Boeing shares declined approximately 1.8% as investors focused on a wider-than-expected adjusted earnings loss and a $697 million operating loss in its commercial aircraft division. These challenges overshadowed improvements in revenue, cash flow, and the company's record backlog.
How much was Boeing's backlog in the third quarter of 2026?
Boeing reported a record backlog of approximately $745 billion, including $612 billion in commercial aircraft, $101 billion in defense, and $33 billion in global services. The commercial backlog represented more than 6,300 aircraft awaiting delivery.
Did Boeing generate positive free cash flow in the third quarter?
Yes. Boeing generated $464 million in free cash flow and $1.50 billion in operating cash flow during the quarter. However, free cash flow remained negative $359 million for the first nine months of 2026.
Why is Boeing's commercial aircraft division still losing money?
Boeing cited an unfavorable aircraft delivery mix, higher estimated supply-chain costs, and projected expenses associated with future production-rate adjustments. The division recorded a $697 million operating loss despite delivering 161 aircraft during the quarter.
What are Boeing's next major production milestones?
Boeing is working toward stabilizing 737 production at 47 aircraft per month, while 787 production remains at eight aircraft per month. The company is also targeting its first 777-9 delivery in 2027 following the certification of the 737-7 and 737-10 variants.
This article was created with AI assistance and reviewed by an editor. For details, please refer to our Terms of Use.
Go Beyond the Market Brief with Market Edge
Follow SharperTrades’ complete approach to trading and investing, combining active trade opportunities through Block Orders, long-term research through Stock Investor, and structured market education through the Swing Trading Masterclass. Try Market Edge for $19 your first month →
Explore Research with Stock Investor
Stock Investor is SharperTrades’ platform for long-term investing research and portfolio management. Members receive research reports, portfolio updates, conviction tracking, and in-depth analysis designed to support disciplined investment decisions.
Explore Active Trading & Income Strategies
Block Orders tracks institutional activity and highlights active trade setups and price behavior across long and short opportunities.
For options-focused traders, Essential Option Income provides a structured approach to options income strategies, while Pro Option Trader offers a broader range of options strategies and trade opportunities.
Think More Clearly with SteadyCapital
SteadyCapital is SharperTrades’ decision-support system for long-term investors, built around the SteadyCapital Method™. Review investment ideas, challenge assumptions, evaluate valuation and risk, compare companies, and think through important buy, hold, add, trim, or sell decisions before you act.
Risk Disclosure
All content is provided for educational purposes only and does not constitute investment advice. Trading involves risk, and past performance is not indicative of future results. Please review our full Risk Disclosure for additional information.