AI Storage Demand Drives Western Digital's Profit Surge, but Supply Concerns Weigh on Shares
Western Digital reports surging revenue, expanding margins, and strong demand for AI data storage. Despite an upbeat outlook, shares face pressure from concerns about AI infrastructure spending, future hard-drive supply, and rising investment costs.
Strong Storage Demand Meets a More Cautious Market
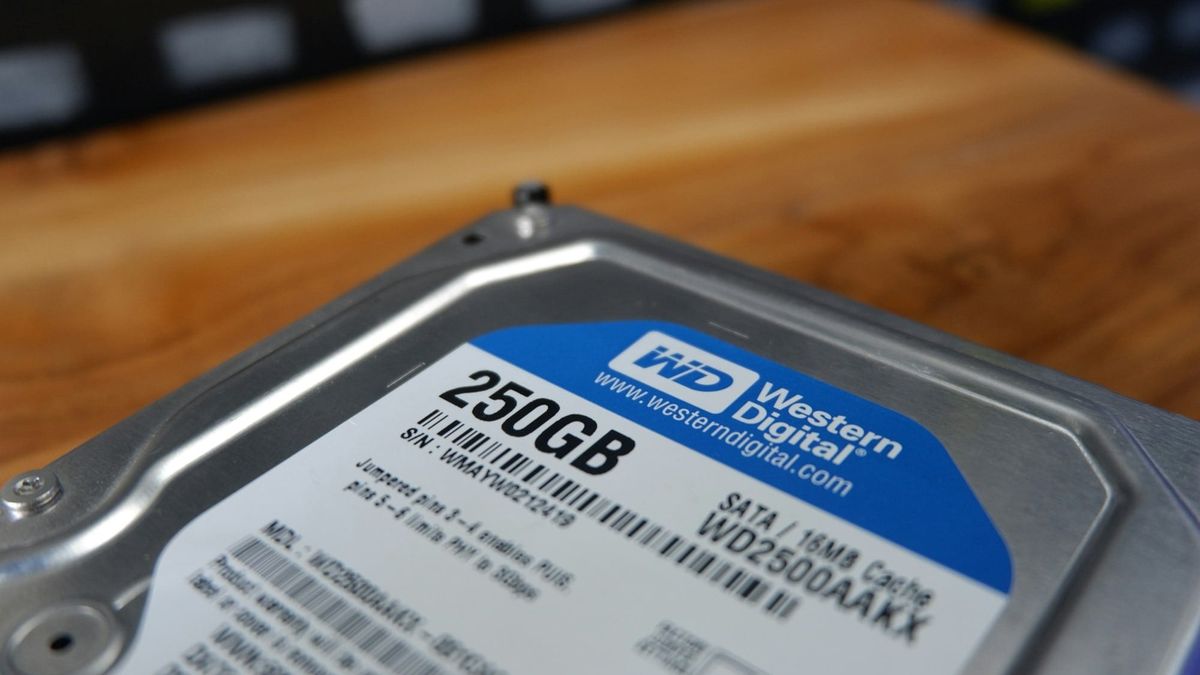
Western Digital (WDC) delivered a strong start to fiscal 2027, reporting sharply higher revenue, expanding profit margins, and an outlook that exceeded Wall Street expectations. Demand for high-capacity hard drives continues to strengthen as cloud providers and artificial intelligence companies expand their data storage requirements.
Yet WDC stock struggled to respond positively. Shares initially fell more than 6% in extended trading following the October 22 earnings release before recovering much of that decline during Friday's session. The mixed reaction highlights growing investor concerns about the sustainability of AI infrastructure spending and whether today's favorable storage pricing can continue as competitors invest in additional supply.
Key Points
- AI storage demand drives growth: Western Digital reported a 55% revenue increase, supported by higher hard-drive shipments, stronger pricing, and growing demand from cloud and AI customers.
- Profitability continues improving: Adjusted gross margin reached 58.1%, while management forecast further expansion and stronger earnings in the fiscal second quarter.
- Investors question sustainability: Despite strong results, concerns about AI spending, potential new industry supply, and higher capital expenditures weighed on the stock's reaction.
Western Digital's Revenue and Margins Surge on Cloud Storage Demand
Western Digital reported fiscal first-quarter revenue of $4.38 billion, an increase of approximately 55% from the previous year and comfortably above Wall Street expectations.
Adjusted earnings reached $4.64 per share, compared with analysts' forecasts of approximately $4.11.
The results reflect a favorable environment for hard-disk drives, or HDDs, which remain an important component of large-scale data storage infrastructure.
Artificial intelligence applications generate and process substantial amounts of information. Cloud operators use high-capacity hard drives to store data that does not require immediate access, creating demand for increasingly efficient storage systems.
Western Digital has benefited from both higher shipment volumes and stronger pricing.
During the quarter, total storage shipments increased 22% from a year earlier, while the average selling price per terabyte rose 28%.
A terabyte measures storage capacity, so higher pricing per terabyte means Western Digital is generating more revenue for a given amount of data storage sold.
That combination has contributed significantly to the company's improving profitability.
Higher-Capacity Drives Support Margin Expansion
Western Digital's adjusted gross margin reached 58.1%, compared with 43.9% a year earlier.
Gross margin measures how much revenue remains after the direct costs of producing and delivering products.
The improvement reflects stronger selling prices, disciplined operations, and a growing contribution from higher-capacity drives.
Adjusted operating margin also expanded substantially, reaching 49.1%.
The company generated approximately $1.38 billion in free cash flow during the quarter, reflecting the cash remaining after capital expenditures.
That financial performance supported shareholder returns, including a 17% increase in the quarterly dividend to $0.175 per share.
Management also outlined a strong outlook for the fiscal second quarter.
Western Digital expects revenue of approximately $5.1 billion, representing year-over-year growth of 66% to 72%.
Adjusted earnings are projected at approximately $5.80 per share, while gross margin is expected to increase further to between 60% and 61%.
The outlook suggests that demand and pricing conditions remain favorable entering the next quarter.
Why Did Western Digital Stock Struggle Despite Strong Earnings?
Western Digital's earnings reaction reflects a broader change in investor sentiment toward companies benefiting from the artificial intelligence infrastructure expansion.
Although demand for AI-related hardware remains strong, investors have become more concerned about the amount of capital required to finance the industry's growth.
Those concerns have weighed on technology stocks, including businesses supplying the infrastructure needed to support AI applications.
Western Digital has experienced significant share-price volatility after a substantial advance earlier in the year.
The company's strong quarterly results and optimistic guidance were therefore weighed against questions about how long current industry conditions can persist.
Could Additional Hard-Drive Supply Pressure Prices?
One concern involves the potential expansion of competing hard-drive production.
A report that Japanese supplier Toshiba (TSHTY) plans to double production capacity for drives used in AI data centers during fiscal 2027 has raised questions about future supply conditions.
The hard-drive industry has historically experienced periods of strong demand followed by increased production and pricing pressure.
Western Digital's recent profitability has benefited from tight supply and rising prices.
If additional capacity becomes available, investors will be watching whether the company can maintain its current pricing strength.
Chief Executive Irving Tan has expressed confidence in the industry's long-term fundamentals.
Management emphasized that Western Digital intends to focus on producing more advanced, higher-capacity drives rather than simply increasing the number of units manufactured.
That distinction is important because greater storage capacity per drive can help the company serve growing data requirements without expanding unit production at the same pace.
Rising Costs and Capital Spending Add Uncertainty
Western Digital is also facing higher costs for certain components used in its products.
Management has a longer-term objective of reducing production costs per terabyte by approximately 10% annually, but near-term progress may be slower because of component inflation.
At the same time, the company expects capital expenditures to run modestly above its long-term framework of 4% to 6% of revenue over the next two years.
Those investments will support new storage technologies, manufacturing automation, and improvements in drive components.
While the spending is intended to improve future product performance and efficiency, it also introduces additional costs during a period when investors are increasingly scrutinizing AI-related capital investment.
The combination of potential competitive supply, input cost pressures, and higher spending helps explain why strong earnings were not enough to produce a sustained positive stock reaction.
What Comes Next for Western Digital's AI Storage Business?
Western Digital expects continued growth in data storage demand as cloud computing and artificial intelligence applications expand.
Management said demand visibility from its seven largest customers extends into 2030 and 2031.
That visibility reflects customers' longer-term storage planning, although it does not mean all future orders and prices are secured under binding agreements.
The company also reported that demand is broadening beyond traditional hyperscale cloud operators.
Enterprise customers, newer cloud infrastructure providers, and AI laboratories are contributing to storage requirements.
Cloud-related business represented 88% of Western Digital's quarterly revenue, highlighting both the importance of this market and the company's exposure to changes in cloud infrastructure spending.
New Storage Technologies Become a Growth Priority
Western Digital is transitioning toward more advanced hard-drive platforms designed to increase storage capacity.
Its latest energy-assisted perpendicular magnetic recording technology, known as ePMR, is already in volume production.
The company expects the platform to represent a growing share of its high-capacity storage shipments.
Western Digital is also preparing heat-assisted magnetic recording, or HAMR, technology.
HAMR is designed to enable higher storage densities, allowing manufacturers to store more data on individual drives.
Initial customer qualifications are targeted for early calendar 2027, with volume shipments expected during the first half of the year.
These product transitions are central to Western Digital's strategy of increasing storage capacity and improving profitability without significantly expanding drive-unit production.
Pricing and Customer Demand Remain Key Variables
Management expects additional opportunities for year-over-year increases in selling prices per terabyte over the next three to four quarters.
Contract renewals, higher-capacity products, and favorable supply conditions are supporting that outlook.
However, longer-term pricing remains less certain.
Although Western Digital has visibility into customers' future storage requirements, the portion covered by firm volume and pricing commitments declines further into the planning horizon.
The company must therefore continue converting customer demand into profitable shipments while managing competitive supply and manufacturing costs.
Analysts remain divided over how durable the current earnings expansion will be.
Melius Research maintained a Buy rating while lowering its longer-term price target, citing continued margin opportunities despite broader AI concerns.
UBS maintained a Neutral rating and reduced its price target, pointing to uncertainty surrounding industry supply and production costs.
Those differing assessments reflect the central debate around Western Digital: whether today's elevated profitability represents a lasting improvement in the business or a particularly favorable phase of the storage industry's cycle.
What It Means for Investors
Western Digital's latest results provide evidence that demand for high-capacity data storage remains strong despite broader concerns about AI infrastructure spending.
The company is benefiting from higher shipment volumes, improved pricing, and a transition toward more advanced storage products.
Those factors have supported substantial margin expansion and stronger cash generation.
However, the stock's muted reaction demonstrates that investors are looking beyond immediate earnings growth.
The sustainability of pricing power is particularly important.
Western Digital's financial performance has benefited from tight hard-drive supply, but potential production increases by competitors could change that balance over time.
Higher capital expenditures and component costs also introduce questions about how much of the company's revenue growth will translate into lasting cash flow.
For investors following WDC stock, the most important developments will be the progression of storage pricing, adoption of higher-capacity drives, and the company's ability to preserve margins as new technologies enter production.
The broader financing environment for AI infrastructure will also remain relevant because Western Digital's customers are closely connected to cloud and data center investment.
Conclusion
Western Digital's fiscal first-quarter results show that the AI-driven storage expansion continues to support strong revenue growth, higher prices, and improving profitability. Management's outlook points to further momentum, supported by customer demand and upcoming high-capacity drive technologies. Yet the stock's reaction reflects uncertainty about future industry supply, rising investment requirements, and the durability of current margins. The next several quarters will help determine whether Western Digital can sustain its earnings expansion as the hard-drive market evolves.
FAQs
Why did Western Digital stock fall despite strong earnings?
Western Digital shares initially declined despite exceeding earnings and revenue expectations because investors remained concerned about AI infrastructure spending, potential increases in competing hard-drive supply, and higher manufacturing investment costs.
How did Western Digital perform in its fiscal first quarter of 2027?
Western Digital reported revenue of $4.38 billion, up approximately 55% year over year, and adjusted earnings of $4.64 per share. Adjusted gross margin reached 58.1%, supported by stronger storage pricing and higher-capacity drive sales.
How is artificial intelligence benefiting Western Digital?
Artificial intelligence applications generate large amounts of data that require storage. Western Digital supplies high-capacity hard drives used by cloud providers, enterprise customers, and AI infrastructure operators, supporting demand for its storage products.
What is Western Digital's outlook for the fiscal second quarter?
Western Digital expects revenue of approximately $5.1 billion, plus or minus $100 million, and adjusted earnings of approximately $5.80 per share. Management also forecasts adjusted gross margin of 60% to 61%.
What are the main risks facing Western Digital?
Key risks include additional hard-drive supply from competitors, rising component costs, increased capital expenditures, and uncertainty surrounding long-term AI infrastructure spending. These factors could affect pricing power, profit margins, and future cash generation.
This article was created with AI assistance and reviewed by an editor. For details, please refer to our Terms of Use.
Go Beyond the Market Brief with Market Edge
Follow SharperTrades’ complete approach to trading and investing, combining active trade opportunities through Block Orders, long-term research through Stock Investor, and structured market education through the Swing Trading Masterclass. Try Market Edge for $19 your first month →
Explore Research with Stock Investor
Stock Investor is SharperTrades’ platform for long-term investing research and portfolio management. Members receive research reports, portfolio updates, conviction tracking, and in-depth analysis designed to support disciplined investment decisions.
Explore Active Trading & Income Strategies
Block Orders tracks institutional activity and highlights active trade setups and price behavior across long and short opportunities.
For options-focused traders, Essential Option Income provides a structured approach to options income strategies, while Pro Option Trader offers a broader range of options strategies and trade opportunities.
Think More Clearly with SteadyCapital
SteadyCapital is SharperTrades’ decision-support system for long-term investors, built around the SteadyCapital Method™. Review investment ideas, challenge assumptions, evaluate valuation and risk, compare companies, and think through important buy, hold, add, trim, or sell decisions before you act.
Risk Disclosure
All content is provided for educational purposes only and does not constitute investment advice. Trading involves risk, and past performance is not indicative of future results. Please review our full Risk Disclosure for additional information.